$300,000 is a realistic number for a lot of dental students today. We ran the numbers on it before. Federal loan rates for the 2026-27 school year came in slightly lower, at 8.07% for graduate unsubsidized loans and 9.07% for Grad PLUS loans, so it's time for an update.
The setup
- $75,000 a year for four years, paid out in two $37,500 disbursements at the start of each fall and spring semester.
- Each year: $50,000 in Direct Unsubsidized loans at 8.07% and $25,000 in Grad PLUS loans at 9.07%. That's $200K unsubsidized and $100K Grad PLUS over four years.
- Interest starts the day each loan is paid out. Nothing is paid during school or the six-month grace period after graduation.
- When repayment starts, the unpaid interest is added to the balance.
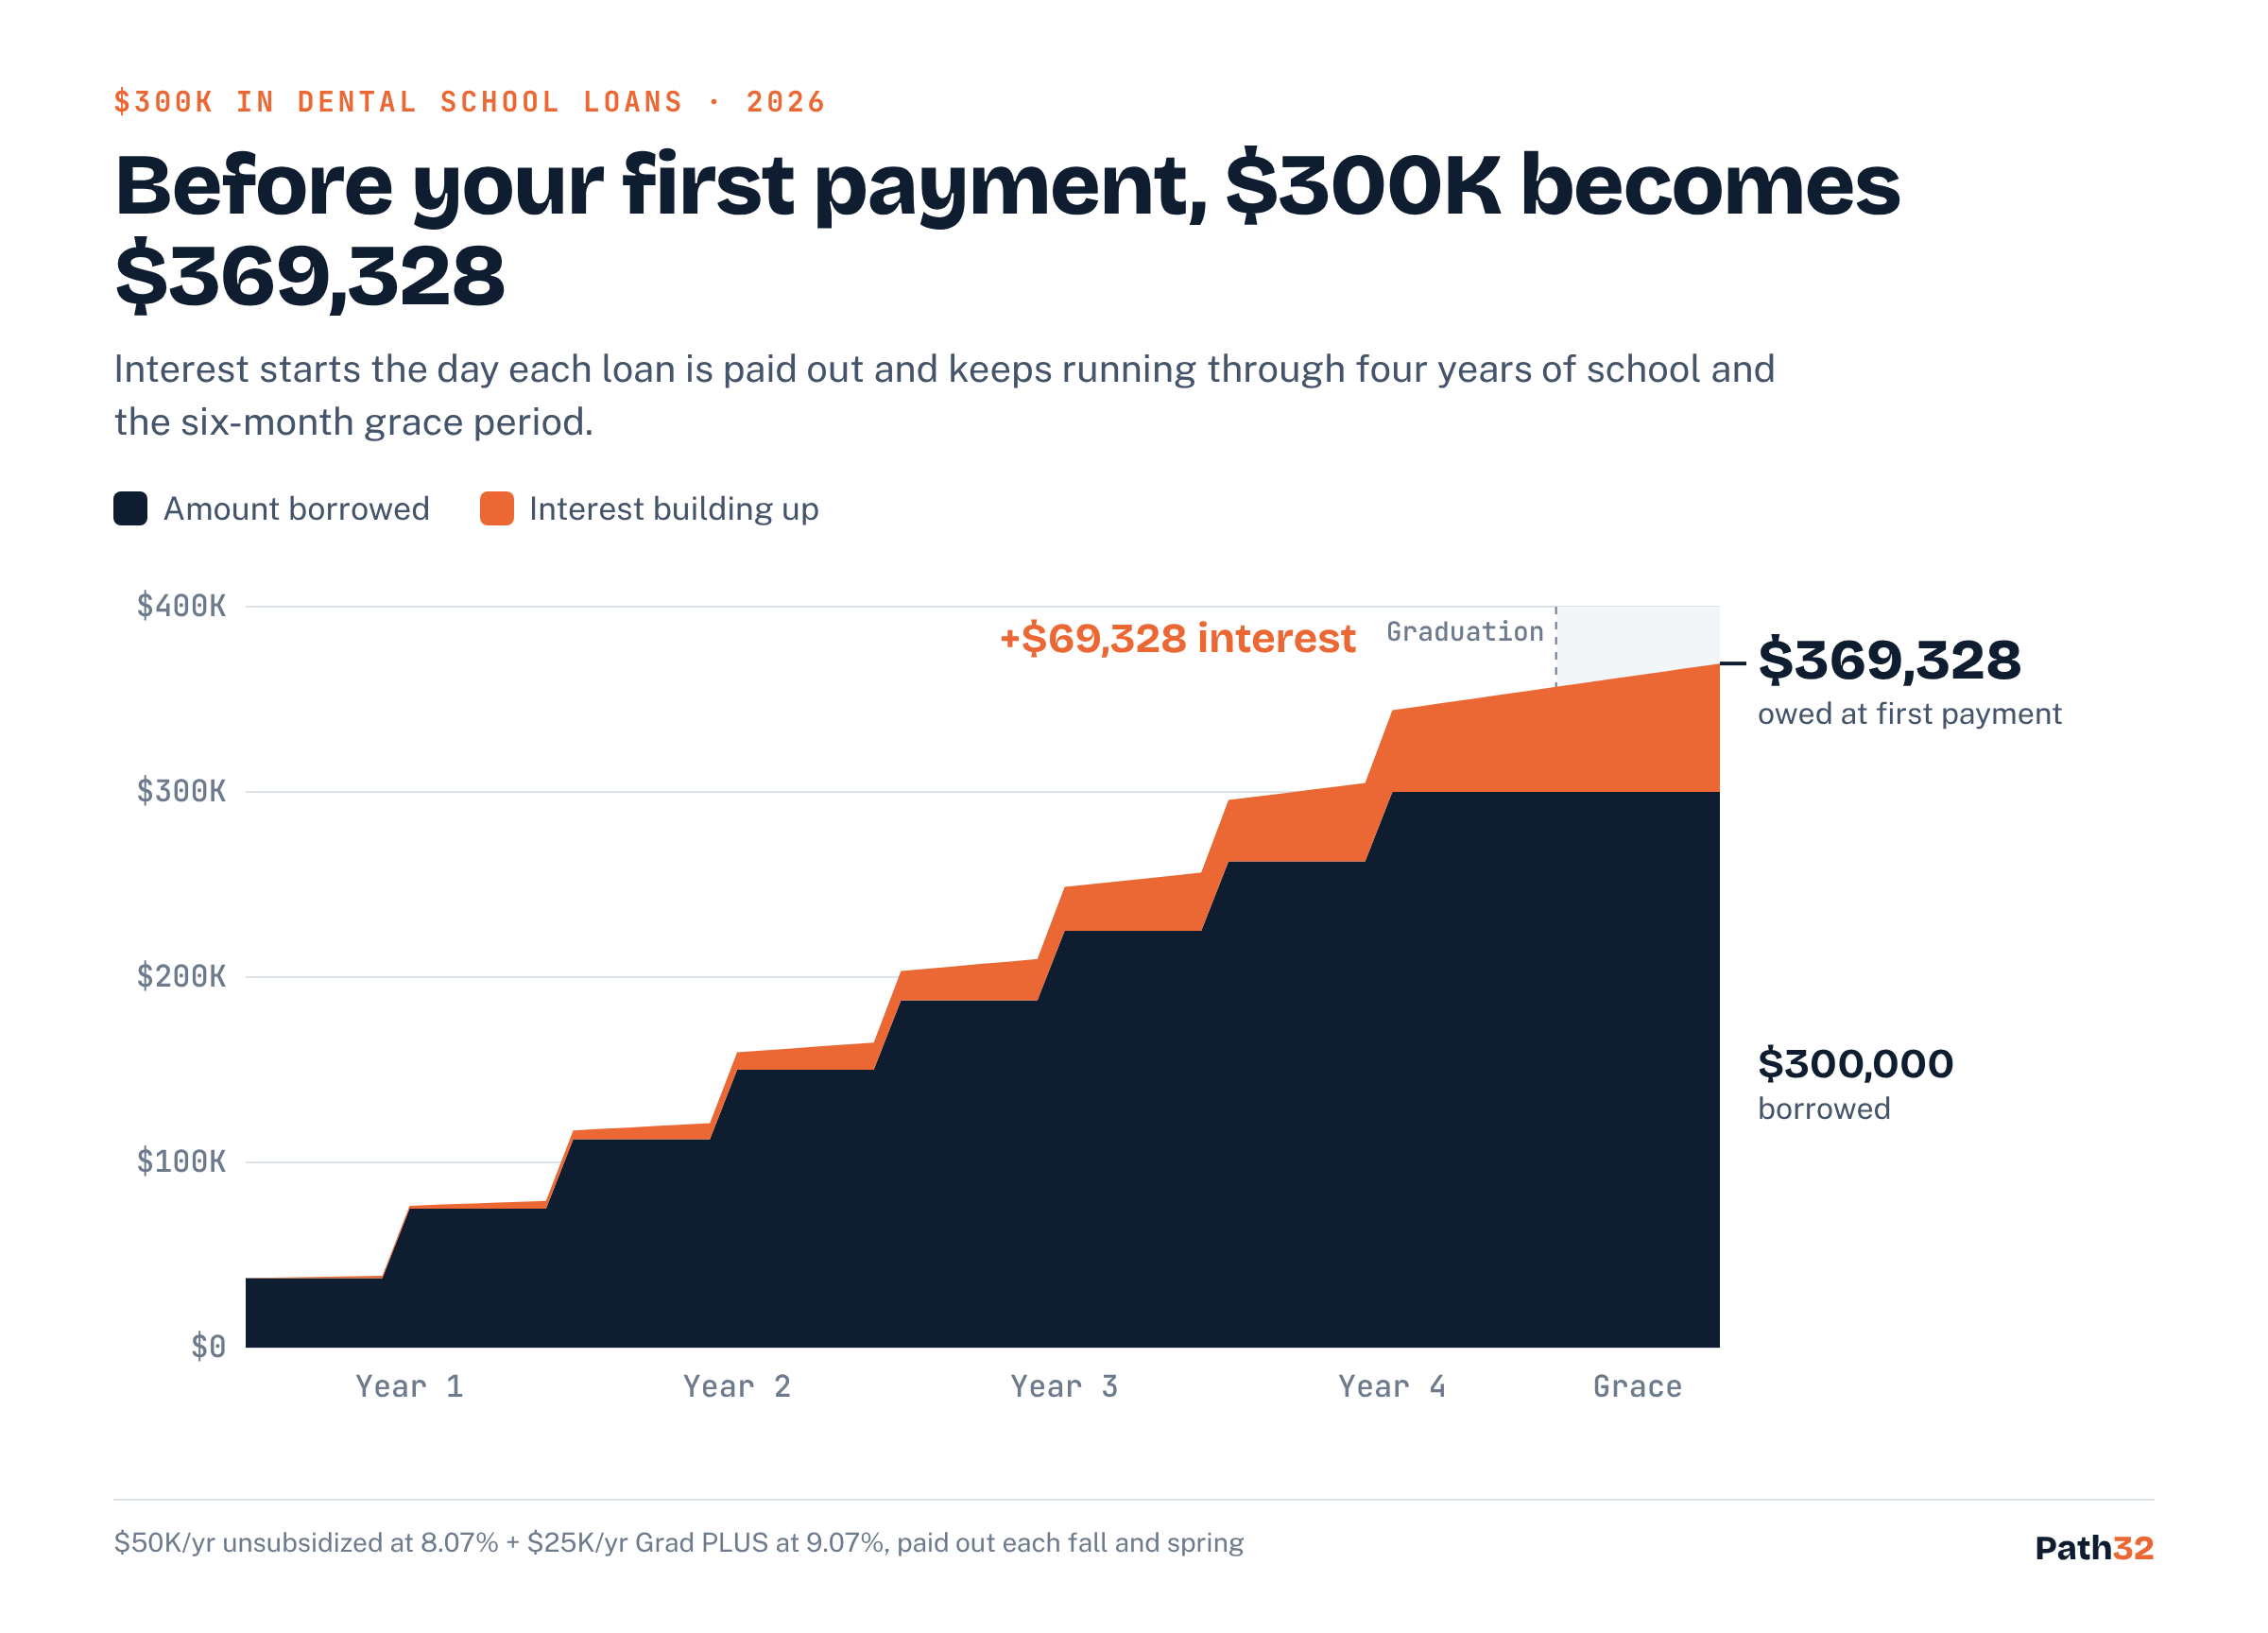
By the time you make your first payment, roughly $69,000 of interest has built up. Your first-year loans have been gaining interest for four and a half years before you pay a dollar back.
Paying it back
Here's what $369,328 costs on a standard fixed-payment plan at each term length:
| Term | Monthly payment | Total paid | Total interest |
|---|---|---|---|
| 10 years | $4,562 | $547,388 | $247,388 |
| 15 years | $3,618 | $651,207 | $351,207 |
| 20 years | $3,185 | $764,296 | $464,296 |
| 25 years | $2,952 | $885,617 | $585,617 |
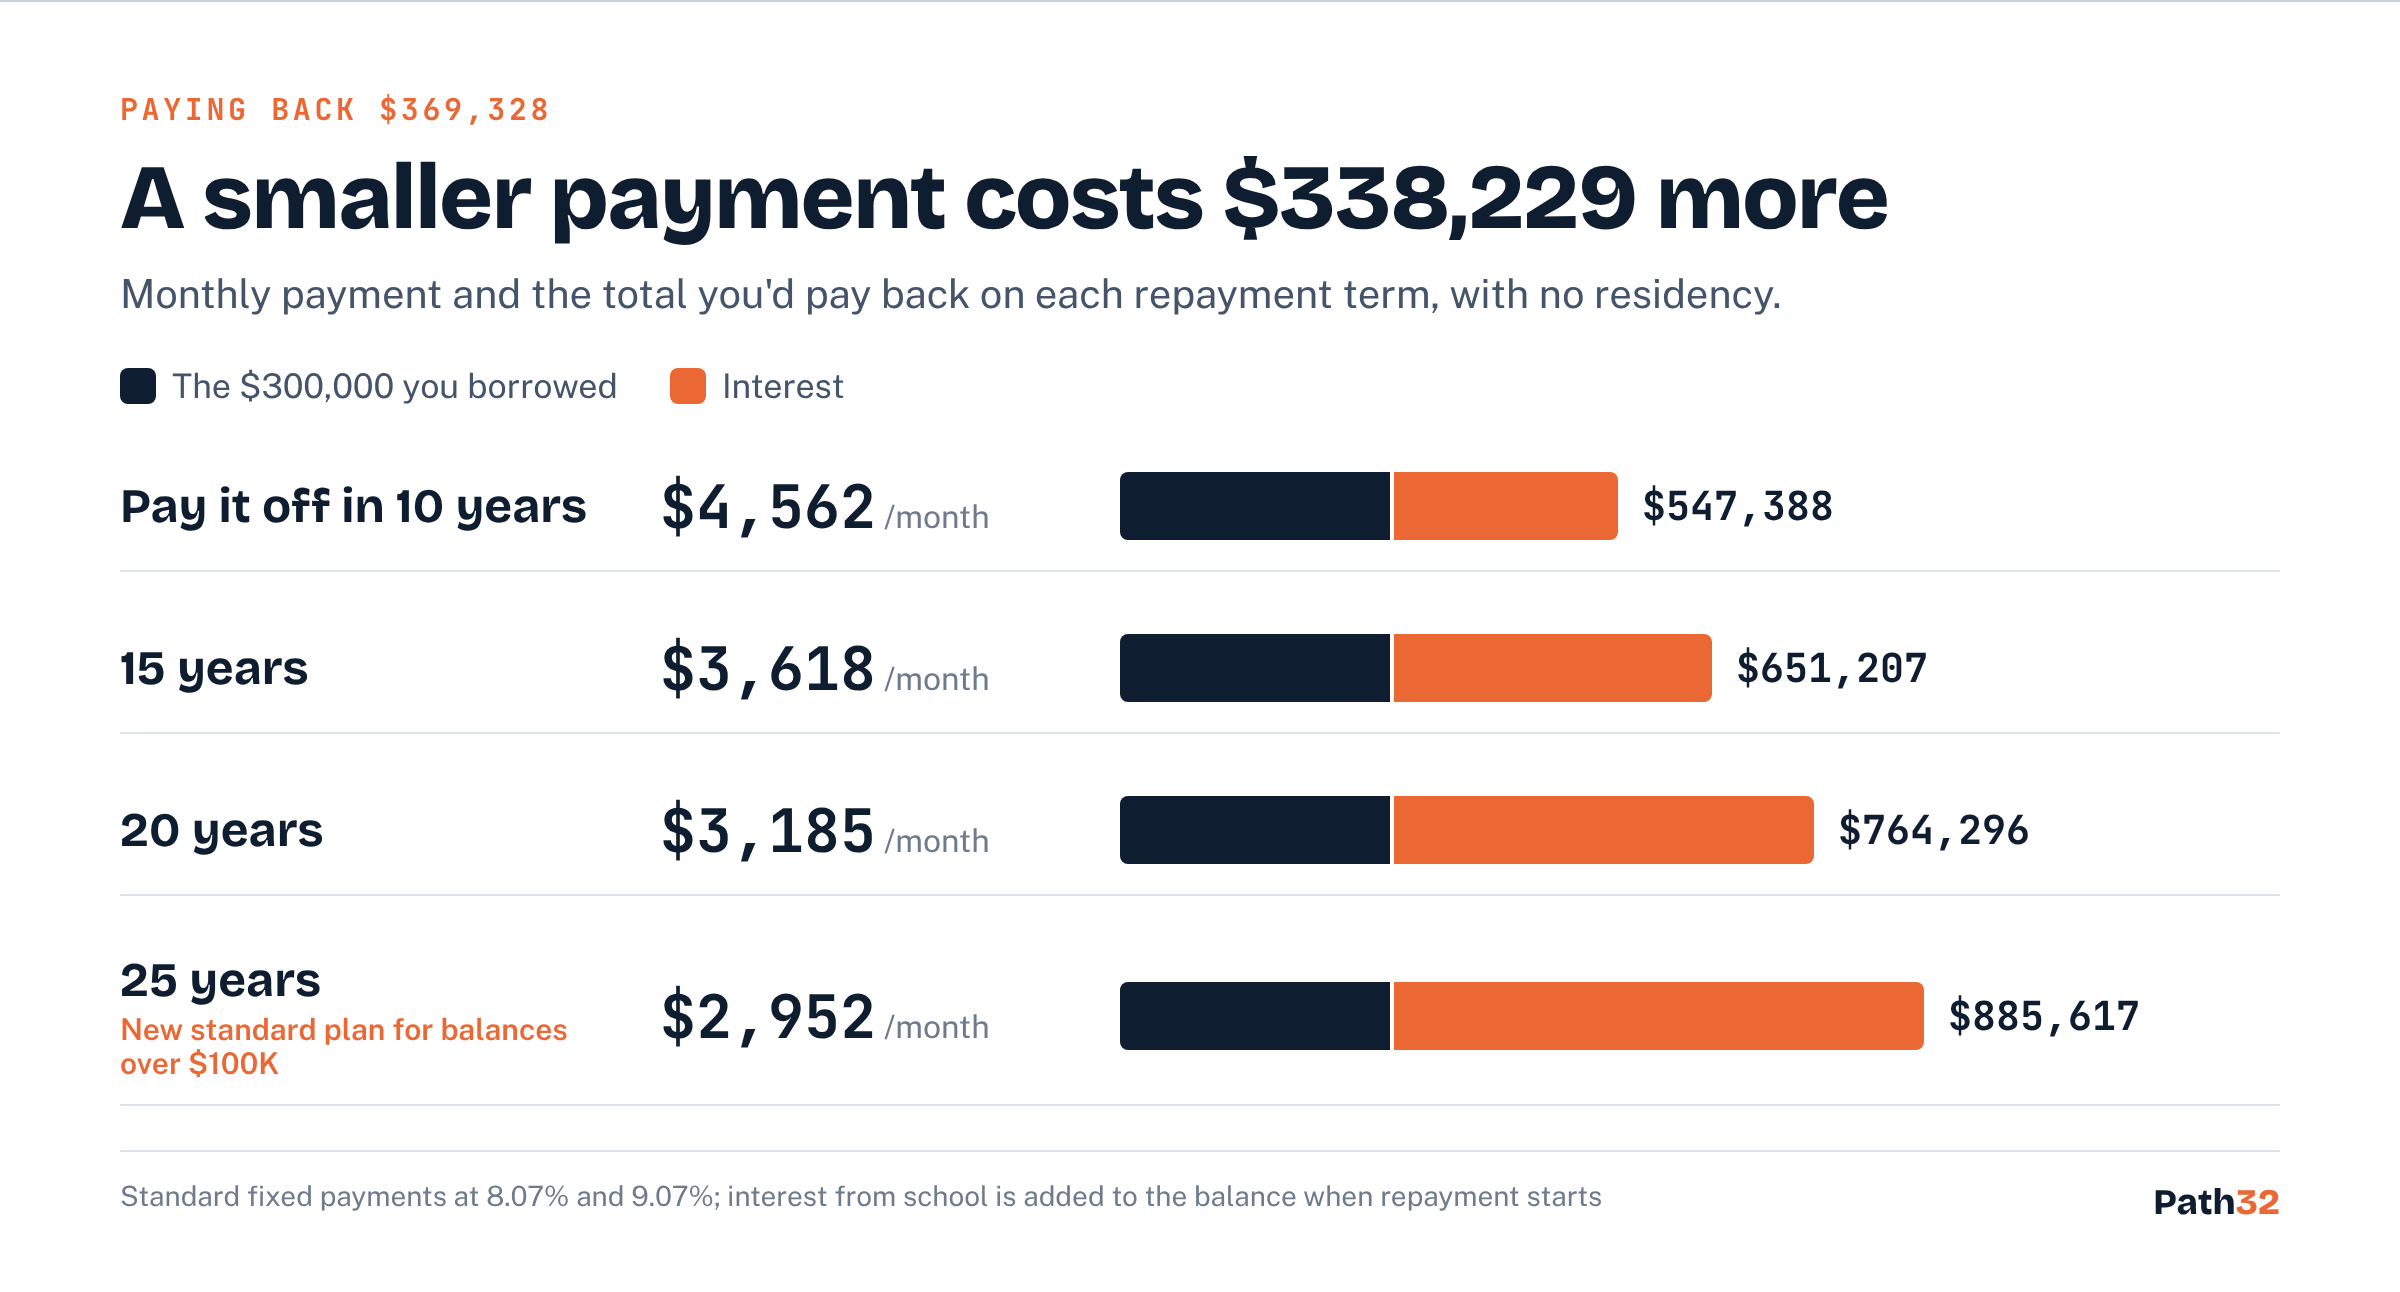
Stretching from 10 to 25 years cuts the monthly payment by about $1,600 but adds $338,229 in interest. That's more than the original loan.
The 25-year term matters more now. For loans made after July 1, 2026, the new federal Standard plan sets the term by balance, and anything over $100K defaults to 25 years. You can always pay more each month to finish sooner, but the default is the slowest, most expensive path. The other main option, the income-based Repayment Assistance Plan (RAP), runs up to 30 years.
Residency adds about $25K a year
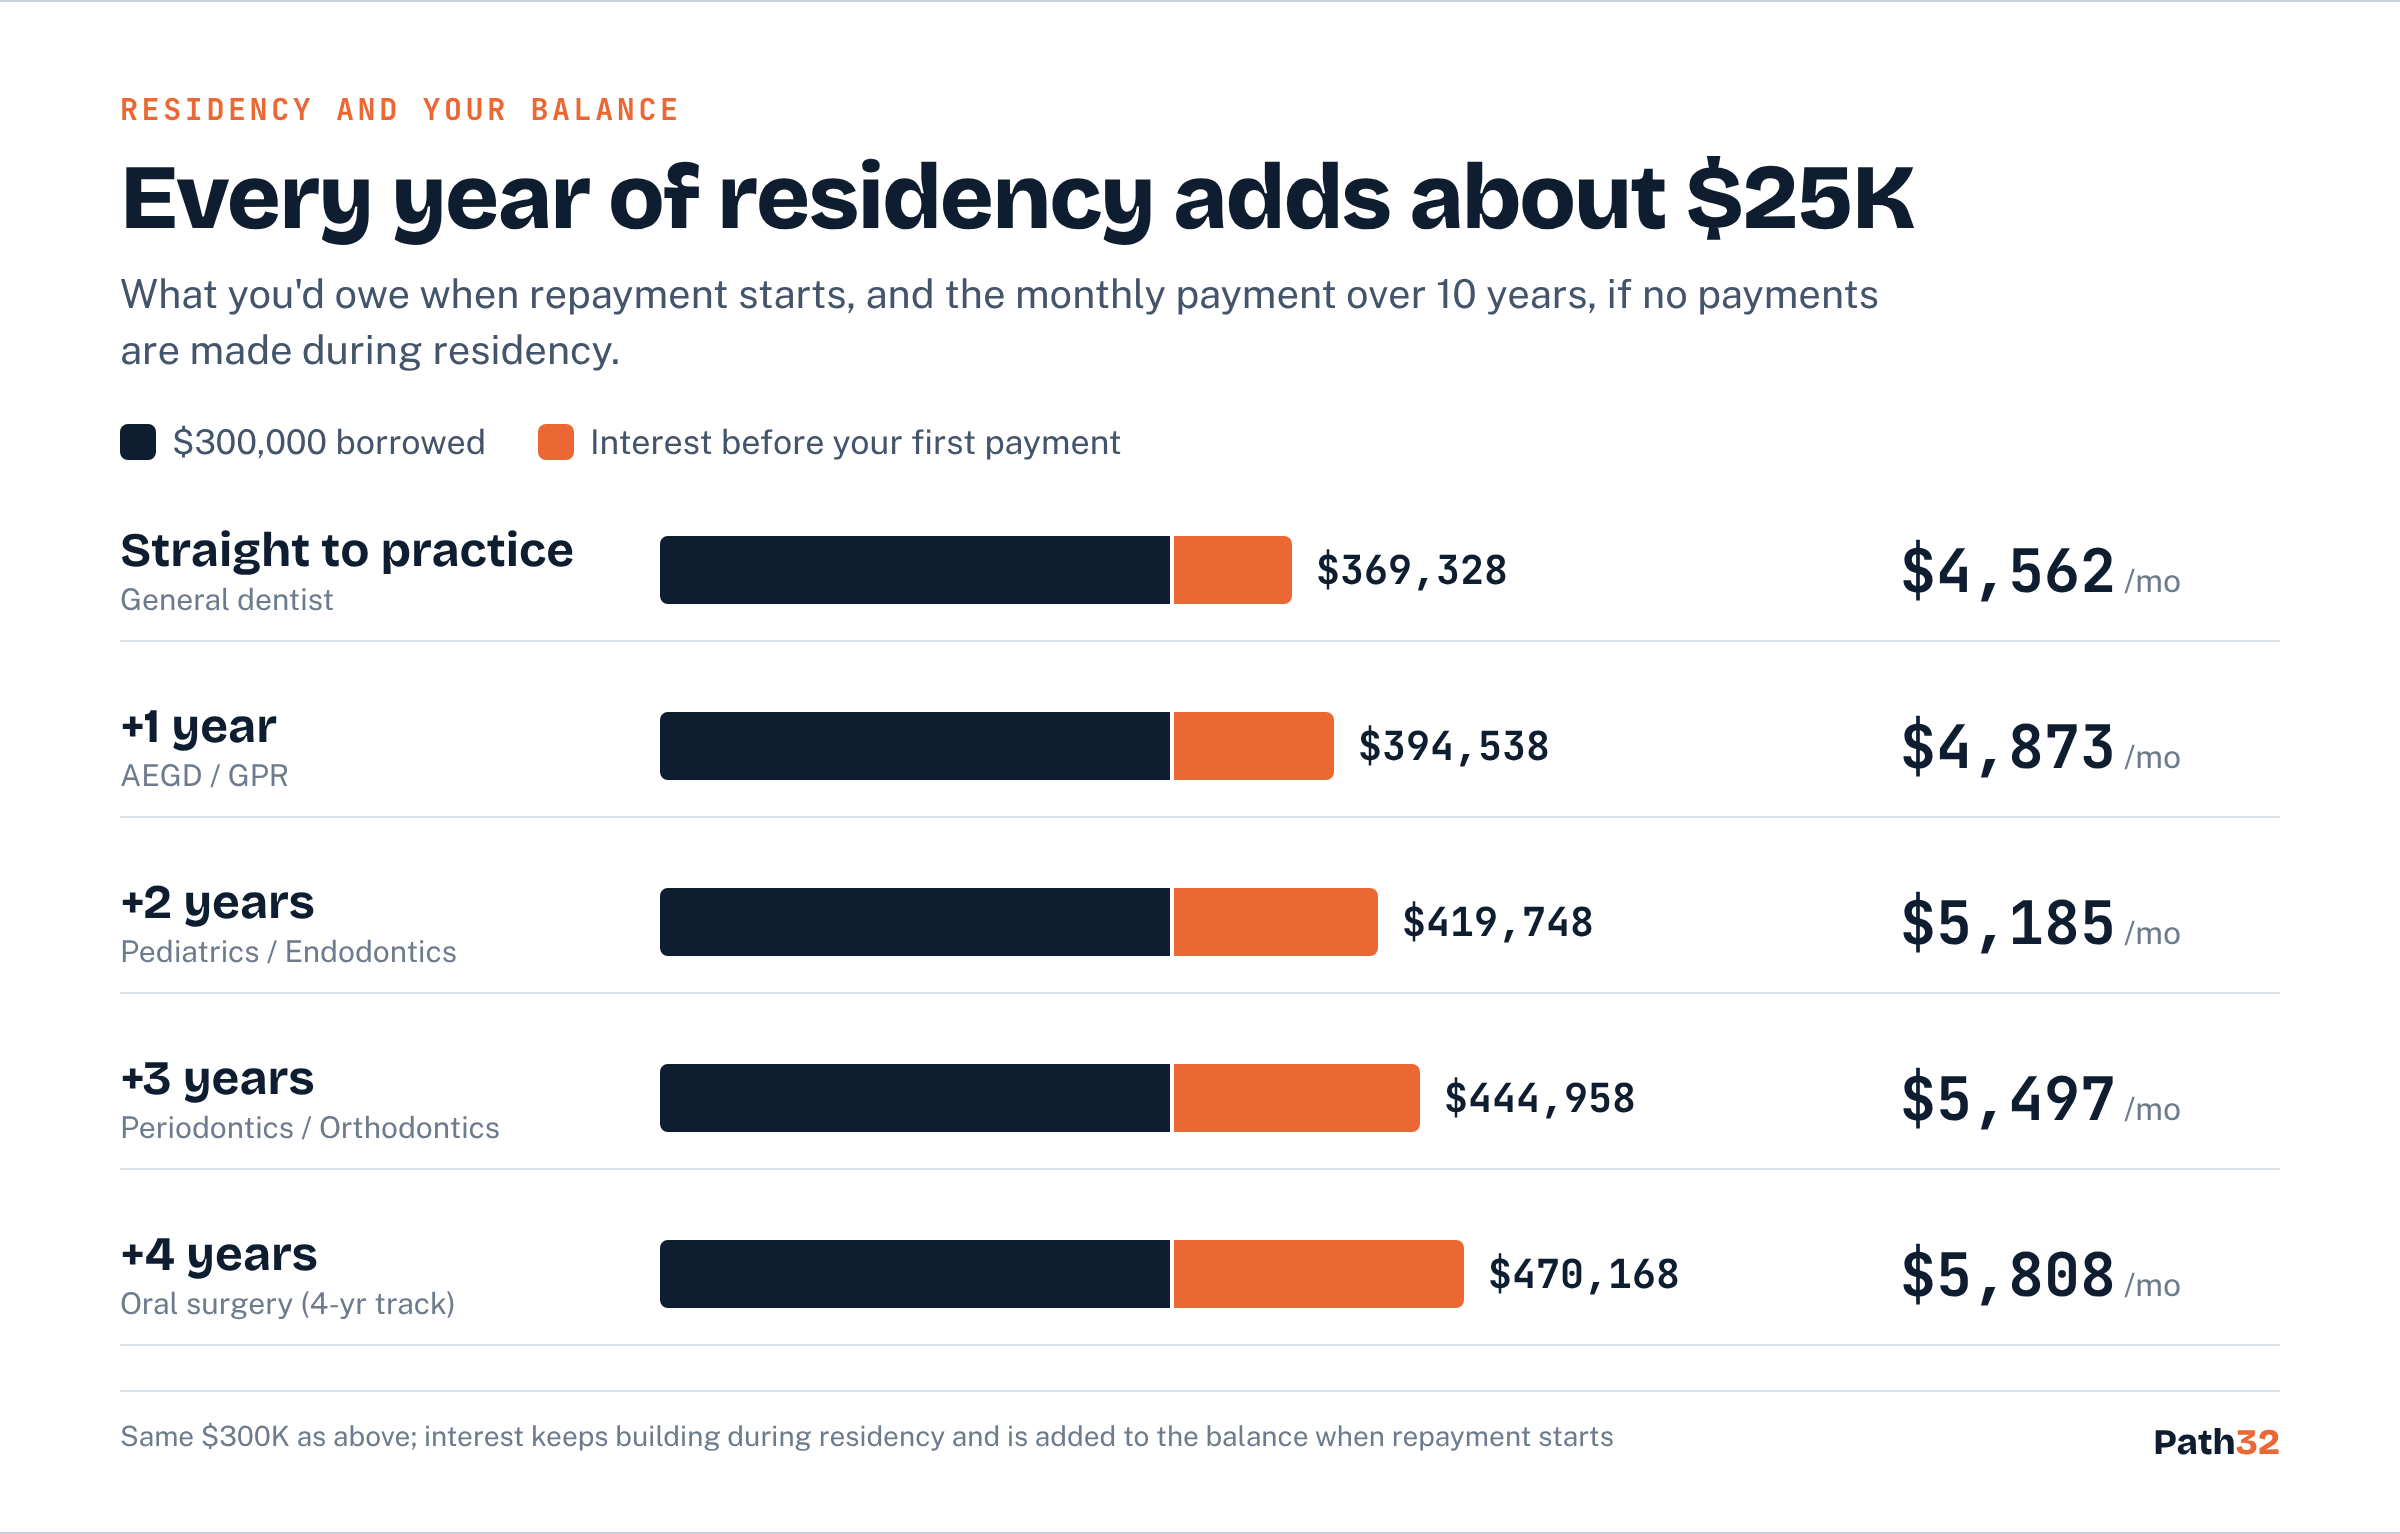
If you go into a residency and don't make payments, interest keeps building. Each year adds roughly $25,000 to the balance.
| Path | Balance at repayment | 10 years | 25 years |
|---|---|---|---|
| Straight to practice | $369,328 | $4,562/mo | $2,952/mo |
| +1 year (AEGD/GPR) | $394,538 | $4,873/mo | $3,154/mo |
| +2 years (Peds/Endo) | $419,748 | $5,185/mo | $3,356/mo |
| +3 years (Perio/Ortho) | $444,958 | $5,497/mo | $3,558/mo |
| +4 years (OMFS) | $470,168 | $5,808/mo | $3,760/mo |
The bigger 2026 change: Grad PLUS is closing
The lower rate barely moves the math: 8.07% instead of 8.08% saves about $3 a month. The rules changed much more:
- Grad PLUS is gone for new students as of July 1, 2026. Students who already borrowed for their current program before that date can keep using it until July 1, 2029.
- New federal limits for professional students: $50,000 a year and $200,000 total in Direct Unsubsidized loans.
- So for the Class of 2030 and later, $300K means $200K federal plus about $100K in private loans. Private loans are credit-based, their rates vary, and they generally don't come with income-driven repayment or forgiveness.
Try your own numbers
Dental school loan calculator
Same assumptions as above: borrowed evenly over four years, two-thirds unsubsidized at 8.07% and one-third Grad PLUS at 9.07%.
The bottom line
- $300K becomes about $369K before you make a single payment.
- A 10-year payoff costs about $4,560 a month. The new 25-year default cuts that to about $2,950, but you'd pay back nearly $886K.
- Each year of residency adds about $25K.
- If you're starting dental school now, plan for federal loans to stop at $200K. Compare tuition, cost of living and in-state options with that cap in mind.
Want to see what you'd be borrowing? Our tuition rankings and out-of-state rankings are a good place to start.
Fine print
- For simplicity, all four years use the 2026-27 rates. In reality, each year's loans get that year's rate, fixed for the life of the loan.
- Monthly payments are standard fixed (amortized) payments. Each loan type is calculated at its own rate.
- Loan origination fees, which are taken out of each disbursement, are not included.
- We assume unpaid interest is added to the balance when repayment begins and that nothing is paid during school, grace or residency. Making interest payments during any of these periods lowers every number above.
- This is an illustration, not financial advice. Check your own loan terms on studentaid.gov.
Sources: 2026-27 federal loan rates; ADEA: borrowing changes for dental school; University of Washington: 2026-27 loan limits; JMU: new repayment plans.